Most business owners carrying short-term business advances didn't get there by being careless. They got there because the marketplace made it easy. A fast approval landed the same week payroll was due, a second offer arrived before the first balance was paid down and the terms were written to be skimmed rather than understood. High frequency payments that felt manageable in a strong month soon added up to high total monthly payments in excess of business cash flow in an ordinary one.
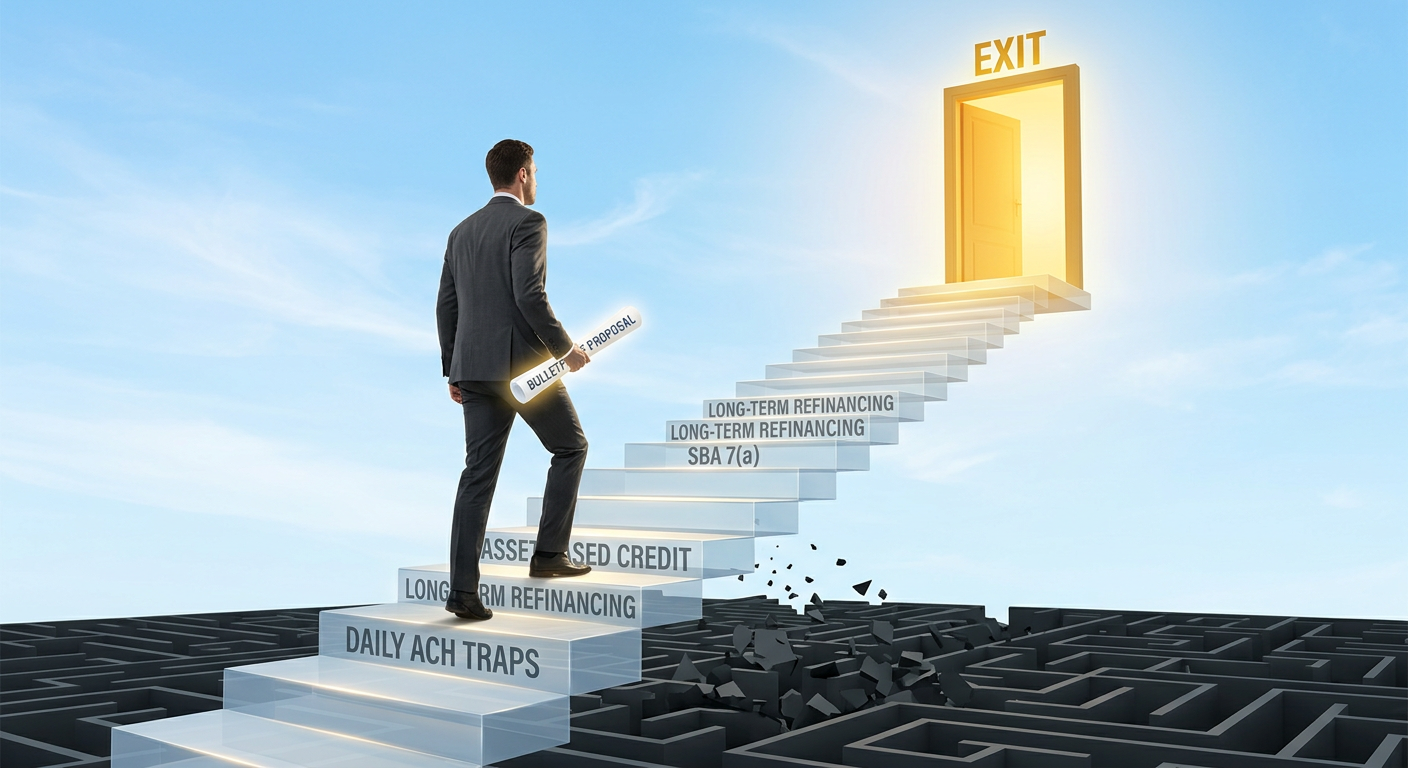
Here is what the aggressive corners of the market rarely mention: there is a different tier of capital built for exactly this moment. Business bridge financing from private credit providers and commercial banks, with payback terms of 18, 24 or 36-months and current market rates in the range of 10.5% to 14.5%, can consolidate those high-cost obligations into one predictable payment stretched out over years, not months, and in many cases adds fresh working capital to the business for growth.
This article walks through how that business bridge loan works, which businesses it fits, what business lenders on this tier want to see and how to position your company to cross it with confidence instead of pressure.
Why the Short-Term Business Lending Market Feels Like Quicksand
The short-term business lending industry is built around speed. Approvals can come in hours, money can arrive in a day or two and the paperwork is light. For a business facing a sudden gap, that speed feels like a rescue. The trouble is what comes after the rescue.
Most short-term business fundings are priced with a factor rate rather than an annual interest rate. The pricing format makes the comparison hard to see, and that is not an accident.
Then comes the stacking. Once one short-term business funding is in place, other providers can see the activity and begin calling with offers of their own. A second position looks like relief from the first. A third looks like relief from the second. Each new layer adds another round of high frequency payments, and soon the business is working hard just to feed its business debt rather than to grow.
None of this reflects a lack of judgment by the owner. It reflects a marketplace designed to reward urgency. The key insight is that urgency-priced capital was never meant to be permanent, and there are better tools for replacing it once the business is ready.
The Hidden Tier of Business Capital Most Owners Never Hear About
Between the fast, expensive world of short-term business financing and the slow, document-heavy world of bank term business loans sits a middle tier that many owners never encounter. This is the world of business bridge financing.
Business bridge financing is designed to carry a company from a difficult position to a stable one. It is longer than short-term business funding, more flexible than a traditional bank product and it is priced on an annual cost of capital rate rather than a factor rate. In today's current business financing marketplace, qualified businesses are seeing rates from roughly 10.5% to 14.5%, with payback terms of 18, 24, 36 and even 48-months.
Why don't more owners hear about it? Partly because the providers on this tier don't advertise the way short-term business advance shops do. They tend to work through relationships with Business Finance Advisors who can present a company's file in a clean, organized way. They are not chasing every inbound call. They are looking for businesses with real revenue and a credible plan, and they price their capital and determine the bridge loan length of payback accordingly.
For a business owner who has been fielding aggressive business funding offers for months, simply learning that this tier exists can change the whole conversation. The question shifts from "How do I survive the next payment?" to "How do I replace this structure entirely?"
How Business Bridge Financing Actually Works
At its core, a business bridge financing transaction for consolidation follows a straightforward path. A business lender reviews the company's revenue, existing obligations, operational profits and overall health. If the file fits, the business lender extends a single facility large enough to pay off the existing short-term business advances and, where the numbers allow, provide additional working capital.
The existing business debt payoffs are usually handled directly. The new business lender requests payoff letters from each existing provider, confirms the balances and sends funds straight to those providers at closing. This protects the business owner from a common trap: receiving a lump sum, intending to pay off the old positions and then facing pressure to use the cash elsewhere while the other high frequency business debt service payments keep running on the other shorter business financings.
Once the old positions are retired, the high frequency payments stop. In their place is a significantly lower total monthly payment on a fixed schedule over 18, 24, 36, and even 48-months. The business knows exactly what it owes, exactly when and exactly when the obligation ends.
Some facilities are structured as straight term business loans. Others include features such as interest-only periods at the start, or a revolving component for ongoing working capital needs. The structure depends on the business lender and on the company's profile, which is why it pays to see more than one option before committing.
The Real Cost Math: Factor Rates Versus Annual Rates
Numbers make this clearer than any description can. Consider an illustrative example. A company has two short-term business financings in place with roughly $250,000 in combined remaining payback. Between the two, high frequency payments add up to about $48,000 per month, high total monthly payments in excess of business cash flow.
Now imagine that company qualifies for a $300,000 business bridge financing facility at 12.5% over 24-months. The monthly payment on that facility comes to roughly $14,200 per month. The two short-term business advances are paid off at closing. The remaining proceeds, after closing costs, become working capital the business can actually use to fund growth objectives.
That single change can free up more than $30,000 a month in business cash flow. Over 24-months, the total interest on the new facility would be around $40,600. Compare that to what continued stacking typically costs, and the difference is often dramatic. Short term business financing of $250,000 over a span of 24-months is likely 2 to 3 “renewals” and can cost up to $400,000 to $500,000 to get short term business financing of $250,000 for 24-months.
The term choice changes the picture as well. On the same $300,000 at 12.5%, an 18-month term carries a payment near $18,400 with total interest of about $30,600. A 36-month term lowers the payment to roughly $10,000, with total interest near $61,300. Across the current rate range, a 24-month facility at 10.5% would run about $13,900 a month, while one at 14.5% would run about $14,500.
Actual terms depend on underwriting, fees and the true payoff balances. But they show the central point: once the cost is expressed as an annual cost of capital rate over a reasonable term, the business owner can finally compare apples to apples, and the comparison usually favors the resulting business cash flow advantage of business bridge financing.
Choosing the Right Runway: Matching Term Length to Your Recovery
Picking between 18, 24, 36 and even 48-months is not just a math exercise. It is a strategy decision about how much breathing room the business needs and how fast it expects to strengthen.
An 18-month term suits a business with strong margins and a clear path to rapid improvement. The total, combined monthly payment is higher, but the total interest is lower and the business is free of the obligation sooner. This option fits owners who mainly need to escape high frequency payments and can comfortably handle a larger monthly figure.
A 24-month term is often the balanced middle. It meaningfully lowers the monthly payment while keeping the total cost contained. For many companies replacing two or three short-term business advances, this is the runway that relieves pressure and provides fresh working capital without stretching the business debt longer than necessary.
A 36 or 48-month term gives the most breathing room. The monthly payment is the lowest, which can make a major difference for a business that is rebuilding margins, investing in equipment or staff, or navigating a seasonal cycle.
A useful exercise is to model all three against a conservative revenue forecast, not the best month of the year. The right term is the one the business can carry comfortably in an average month, with room left over for growth and the unexpected.
Private Credit Versus Commercial Banks: Two Doors to the Same Bridge
Business bridge financing comes from two main sources, and each has its own personality.
Private credit providers have grown rapidly over the past several years. They are typically faster than banks, more flexible about structure, and more willing to look at the full story of a business rather than a narrow checklist. They may accept a company that has recently used short-term business advances, as long as revenue is solid and the consolidation and recapitalization plan makes sense. Their pricing often sits toward the middle or upper end of the current 10.5% to 14.5% annual cost of capital range, reflecting that flexibility.
Commercial banks, by contrast, tend to offer pricing toward the lower end of the range, yet tend to approve slightly less total financing amounts, for businesses that meet their standards. Their underwriting is usually more detailed, their timelines can be longer and they often place more weight on time in business, tax returns, collateral and credit history. For a company with a strong financial profile that simply got caught in the stacking cycle, a commercial bank-backed bridge can be an excellent outcome.
Neither door is automatically better. A company that needs to close quickly to stop the bleeding may be best served by business private credit now, with a plan to move to more traditional bank business financing later. A company with clean books and some patience may be able to go straight to a bank. Understanding both paths lets the owner choose with intention rather than taking whatever arrives first.
What Business Lenders on This Bridge Tier Want to See
Business lenders offering bridge facilities are looking for confidence. They want to know the business is real, the revenue is durable, the management is solid and the consolidation will genuinely improve the company's position. Preparing for that review is one of the most valuable steps an owner can take.
Most business lenders on this tier will ask for 6 to 12-months of business bank statements or more, recent and historical financial statements, a list of current obligations with balances and payment amounts and basic information about ownership and time in business. Many will also want business and personal tax returns. A clear schedule of existing short-term business debts (business debt schedule), including each provider's name, original amount, remaining balance and payment frequency, makes underwriting faster and cleaner.
They will look closely at business cash flow over the trailing 6 to 12-months. Specifically, they want to see that the business generates enough consistent operating profit to carry the new monthly payment with room to spare. A company that is profitable on an operating basis but squeezed by short-term payback, expensive business debt is often exactly the profile these business lenders are built to serve.
It also helps immensely to present an institutional business credit package with a brief (credit memo), explaining how the transactional business debt stacking happened, what has changed in the business and how the freed-up business cash flow will be used shows the business lender a thoughtful operator rather than a desperate one. That framing can influence both approval and pricing.
Turning Freed-Up Business Cash Flow Into Growth Capital
Business debt consolidation is the immediate win, but it is not the whole opportunity. When high frequency payments stop and much lower and manageable payments take their place, the business suddenly has room to think beyond survival.
Many business bridge financing facilities are sized to include working capital beyond the payoff amounts to provide the proper liquidity levels to the business. That capital can fund inventory ahead of a busy season, hire the team member the company has needed for a year, upgrade equipment or launch the marketing push that was always postponed. Instead of new business borrowing at urgency pricing for each of those needs, the business has a planned reserve at a sensible rate.
The monthly cash flow savings matter just as much. In the earlier example, freeing up more than $30,000 a month changes what the business can do. Some owners use that difference to build a cash liquidity cushion so they never again face the kind of gap that started the cycle. Others reinvest it deliberately into the parts of the business with the strongest returns.
The goal is to make the bridge a launching point, not merely a rescue. A company that uses the breathing room well can emerge in as soon as 12 to 18-months with stronger financials, a better credit profile, much more cash on hand and access to even more favorable business financing options going forward.
Avoiding the Re-Stack and Protecting the Business After the Bridge Financing is in Place
One of the quiet risks after a successful business debt consolidation is the phone calls. Once the old positions are paid off, the business can look attractive again to short-term business funding providers, and the offers may start arriving immediately. The pitch is familiar: fast money, no hassle, just in case.
Protecting the business means deciding ahead of time how it will handle those offers. Many bridge agreements include covenants that restrict additional business borrowing without the business lender's consent, which is actually a helpful guardrail. Even where no such restriction exists, setting an internal rule that no new short-term business advance will be taken without a full cost review can prevent the cycle from restarting.
A simple weekly review of business cash flow also helps. Tracking revenue, the new payment, operating costs and cash flow gives the owner early warning of a coming gap. When a business cash flow gap is spotted early, there is time to arrange planned, reasonably priced business funding rather than reaching for whatever is fastest.
Finally, keeping the relationship with the bridge provider strong pays dividends. A business that makes its payments on time and communicates openly often finds that the same business lender is willing to discuss additional capital or even better and longer terms down the road.
Working With a Business Finance Advisor to Build the Existing Business Debt Refinancing Bridge
The business bridge financing marketplace is less visible than the short-term business advance world, and that is precisely why guidance matters. A Business Finance Advisor who works with private credit providers and commercial banks can help an owner see the full menu of options rather than only the ones that happen to call, email and text incessantly.
A good Business Finance Advisor starts by understanding the company's real position: current obligations, true payoff balances, recent revenue, operating patterns and goals. From there, the work involves organizing the file, modeling 18, 24 and 36 and even 48-month scenarios, then presenting the company to the business lenders most likely to approve it at competitive terms. That preparation can shorten timelines and strengthen the final offer.
Just as important, a Business Finance Advisor can help an owner read the fine print. Prepayment terms, fees, covenants and reporting requirements vary widely, and the cheapest-looking offer is not always the best fit. Having someone on the business owner's side of the table, rather than the Business financing provider’s side is a meaningful protection in a marketplace that has not always been kind to business debt borrowers.
For companies caught in the cycle of costly short-term business funding, the business bridge financing option is real and it is within reach. With the right structure, the right term and the right partner, the business can trade high total monthly payments in excess of business cash flow for a clear plan, steady payments and working capital to grow.
More Business Finance and Strategy Articles: