A Business Turnaround Plan is not a suggestion; it's a brutal, immediate action to halt the bleeding, stabilize the cash position, and force profitability back into the ledger.
This process is a high-stakes financial war fought on three fronts: aggressive cash flow correction, ruthless balance sheet restructuring, and a total overhaul of the profit and loss statement.
You must abandon sentimentality, embrace radical change, and execute with an almost militaristic discipline to extract the business from its current downward spiral and forge a sustainable, profitable entity.
The Unflinching Diagnosis: Confronting Financial Collapse
The first step in any genuine turnaround is abandoning the delusion of "temporary trouble."
Your financial statements are not just signaling weakness—they are screaming insolvency if left unchecked. You must immediately conduct a forensic-level financial audit. Forget the glossy summaries and drill down into the granular data.
Your Profit and Loss (P&L) statement must be dissected to identify the exact point of value destruction.
Which product lines or customer segments are draining resources and masking losses?
Pinpoint the fixed and variable costs that have inflated beyond reasonable levels. Simultaneously, your Balance Sheet must be treated as a liability map. Aggressively write down or sell all non-performing assets, liquidate obsolete inventory that is tying up capital, and scrutinize accounts receivable for uncollectible debt.
This diagnostic phase is about establishing the True Financial Picture—the ugly truth that will inform the necessary, painful cuts and capital injections to come. Without this ruthless clarity, any subsequent action is simply a gamble.
Cash Is King, and Yours Is Dying: Immediate Cash Flow Stabilization
Cash is the oxygen, and your business is suffocating.
The immediate priority is cash flow triage—stopping the burn and extending your runway. This means an immediate, non-negotiable crackdown on Accounts Receivable (AR). Stop granting generous credit terms and adopt an aggressive collection policy. Offer steep discounts for immediate payment and be prepared to use every legal means necessary to reclaim overdue funds.
Simultaneously, you must exert maximum pressure on Accounts Payable (AP). Engage your key suppliers immediately. Do not apologize; present your credible turnaround plan and negotiate extended payment terms, demonstrating that it is in their financial interest to keep you viable.
Implement an across-the-board Capital Expenditure (CapEx) freeze and immediately divest any underperforming or non-essential assets to generate quick cash. Every day that passes without a positive shift in your cash position is a day closer to failure.
The Profit and Loss StatemeNT Overhaul: Extracting Profit from Pain
Your existing P&L structure is a roadmap to failure; it must be completely dismantled and rebuilt.
The focus shifts from top-line revenue to gross profit margin and operational leverage.
Begin with Cost of Goods Sold (COGS). Aggressively renegotiate vendor contracts, demand deeper volume discounts, and simplify product specifications to reduce input costs. If a product line does not generate a predetermined, acceptable gross margin, it is immediately cut or outsourced.
Next, attack Operating Expenses (OpEx) with a hatchet, not a scalpel. Challenge every single line item. This means non-essential salaries, excessive marketing spend, redundant technology licenses—all must go. Implement zero-based budgeting where every expense must be justified from a base of zero.
This is where the emotional resilience is tested: you must make the personnel cuts and operational closures that align with the core, profitable segments, ignoring all legacy attachments.
Balance Sheet Warfare: De-Leveraging and Asset Discipline
A weak balance sheet is a ticking bomb. The turnaround demands aggressive de-leveraging and asset optimization. Review every debt obligation. Negotiate with lenders for interest-only periods, covenant waivers, or a restructuring of principal payments based on your new, credible financial projections.
You must demonstrate that the business, post-restructuring, has a clear path to debt service coverage. On the asset side, inventory must be managed with extreme prejudice. Liquidate slow-moving or obsolete stock at cost if necessary—the cash locked in those goods is more valuable than the theoretical margin. Ensure your working capital cycle is minimized; if it takes too long to convert raw materials into cash, your operational model is broken and needs immediate redesign.
A strong balance sheet means maximizing liquidity and minimizing risk, freeing up collateral and credit capacity for the inevitable next stage of investment.
Refocus and Reposition: The Core Competency Mandate
Businesses often fail because they lose focus chasing fleeting opportunities that dilute resources. Your turnaround demands a singular, ruthless strategic focus.
Analyze your P&L data to identify the one or two core products or services that generate the highest sustainable margins. Everything else is a distraction. Immediately divest, outsource, or discontinue the non-core activities, regardless of historical volume or pride of ownership.
This aggressive segmentation allows you to concentrate all remaining financial resources—labor, marketing spend, and CapEx—on the areas where your business can dominate and dictate price. Your new value proposition must be narrow, specific, and backed by a cost structure that is superior to your competition in that specific niche.
Funding the Fight: Securing Credible Capital
To survive, you will likely need an immediate cash infusion to bridge the stability gap.
Securing capital in a turnaround is an exercise in selling a vision of recovery, not begging for a bailout.
You must present lenders and potential equity investors with the stress-tested financial model derived from your P&L and Balance Sheet overhaul. Show them the cuts made, the efficiencies gained, and the clear path to positive EBITDA and debt service capacity.
Explore all structured finance options: asset-backed lending (ABL) against your remaining quality receivables and inventory, or even factoring to unlock immediate cash at a cost. If external financing is unattainable, you must demand a capital contribution from the owners or liquidate more assets. Every negotiation requires absolute transparency and a willingness to accept stringent reporting covenants.
The goal is to secure enough capital to execute the operational plan, not to merely fund prior losses.
The Leadership Hammer: Talent Alignment and Accountability
A turnaround demands a leadership shift from consensus-building to decisive, centralized authority. Your management team must either commit fully to the brutal execution of the plan or be replaced immediately. There is no room for passive resistance or mediocrity. Identify and retain only the A-players who are intellectually and emotionally aligned with the new, leaner, aggressive structure.
Every remaining employee must be indoctrinated into the new culture of financial discipline. Implement a rigorous accountability structure tied directly to the turnaround KPIs—cash flow targets, margin adherence, and cost reduction milestones. Compensation and bonuses must be entirely based on achieving these financial targets. The people who remain must be focused, hardworking, and energized by the fight for survival; anything less is a liability you cannot afford.
Execution: The Turnaround Dashboard and Weekly Rhythm
A plan is worthless without fanatical execution. You must establish a Turnaround Dashboard consisting of no more than eight leading financial and operational indicators that you review daily or weekly, not monthly. Key metrics must include Daily Cash Position, AR Collections Rate, Gross Margin by Core Product, and OpEx Variance to Budget.
Implement a mandatory weekly operational review meeting—short, intense, and focused solely on variances from the plan. No excuses are tolerated; every deviation requires an immediate corrective action assigned to a single, accountable individual. This aggressive, high-frequency monitoring system ensures that errors are caught and corrected within days, not weeks or months. This is where the execution is proven—the discipline to stick to the plan even when it becomes uncomfortable.
Sustainable Dominance: Embedding Financial Discipline
The ultimate victory is not survival; it is the creation of a fundamentally more robust, financially disciplined, and profitable enterprise. Once the immediate crisis passes, the aggressive practices—the tight cash control, the rigorous P&L adherence, the minimal working capital—must become the permanent culture.
Institutionalize the weekly dashboard review and maintain the high standard of accountability. The capital freed up by the turnaround must be reinvested strategically back into the core, high-margin areas that secured the business's survival. Your past failure was a costly lesson; the permanent embedding of this financial and operational discipline is the only path to long-term market dominance. Your new business model must be inherently resilient to market pressures.
What is the Best Way to Deal with Business Debt Payments that are causing Business Cash Flow issues?
It is NOT by stopping ACH payments.
It is NOT by taking on another business loan.
It is NOT ALWAYS a Refinancing
It is NOT by entering into a debt settlement program.
Find out the BEST strategies to get your Business back to where it was
More Business Finance and Strategy Articles:
Your business may be in immediate danger. This is not a drill, and it is not a gentle suggestion to review your accounting practices. If you are reading this because your business is drowning in debt and negative cash flow, you are standing on the precipice of total insolvency, and the ground is crumbling beneath your feet.
The sleepless nights, the dread of opening your email, the pit in your stomach when the phone rings—these are not just symptoms of stress; they are the warning lights of a catastrophic engine failure.
Your business is heading towards dying. It is harsh to say, but if you do not acknowledge the severity of your situation, you may risk losing everything you have built. The time for optimism and "waiting for the big deal to close" is over. You are in a war for business survival.
There is a better way. Longer-term business financing, structured properly, can often cost roughly half as much as high-cost short-term debt and stretch repayment over years instead of months. That combination can cut your monthly payments dramatically and hand control of your business cash flow and operations back to you.
This article explains how short-term and expensive business debt traps work, what longer-term business financing look like, how to compare offers honestly and how to prepare your business to qualify. Before you sign for another dollar of business financing, read this first. The right decision today could save your business on costs and cash flow, and a great deal of stress.
When the payments on a costly business loan or merchant cash advance (MCA) start squeezing your business, the first instinct is to call the person who arranged it. They know your file, they know the lender, and they answered the phone quickly the last time you needed money. It feels like the natural place to start.
It is usually the wrong place. Most financing brokers are paid when new money is placed, not when your total cost goes down. They also have every reason to defend the deal they already sold you. Asking them for a way out is like asking the salesperson who sold you the car with the bad transmission whether you should buy another car from the same lot.
This article explains why that conflict exists, how to recognize when you are being steered instead of helped, and what a genuinely independent business finance advisor can do that a broker cannot. If your business is carrying debt that feels heavier every week, read on before you make the next call.
You went looking for capital to help your business grow, steady its cash flow or get through a tough season. You found a lender who approved you quickly, wired the money within days and made the whole process feel easy. Months later, the aggressive debits tied to a short payback period are draining your operating account, your vendors are waiting longer to get paid and the capital that was supposed to help your business is now the biggest threat to it.
This is not bad luck. It is the predictable result of borrowing from high-cost lenders whose business model is built around their own risk, not your ability to repay. Many of these lenders never asked the one question that matters most: after every operating expense is paid, can this business actually afford the business debt payment?
This article explains how these lenders work against the businesses they fund, why their approval should never be mistaken for a sign of affordability and what better-aligned capital looks like for a small to medium-sized business today. If you are already caught in the cycle, the most important step is recognizing it and taking action before the damage reaches your operations.
Your business might be profitable on paper and you still feel broke every single week. If that sounds familiar, the problem may not be your sales, your margins or your work ethic. It may be the shape and structure of your business debt.
When business loans and advances are structured to be paid back faster than the money they fund can earn a return (ROI), every payment pulls cash out of business operations before it has a chance to do its job. Payroll gets tight, suppliers wait and owners start borrowing again just to cover the last loan payments.
The good news is that this is a structural problem, and structural problems have structural fixes. This article explains how short-term business debt payback creates business cash flow strain, how to spot it in your own numbers and what practical steps you can take to restore breathing room and get your business back on solid ground.
If your business is making payments to one or more merchant cash advance (MCA) or short-term business lending companies, you already know the feeling. Revenue comes in, and before you can pay your suppliers, your crew, or yourself, a large share of it is gone. You took the first advance to solve an urgent problem. You took the second to cover the payments on the first. Now the payments are running the business instead of the other way around.
You are not alone, and you are not out of options. Thousands of healthy, revenue-producing companies end up in this exact position every year, not because the business is broken, but because the financing is. Short-term business debt was never designed to be permanent capital, and when it is used that way, it quietly drains even strong operations.
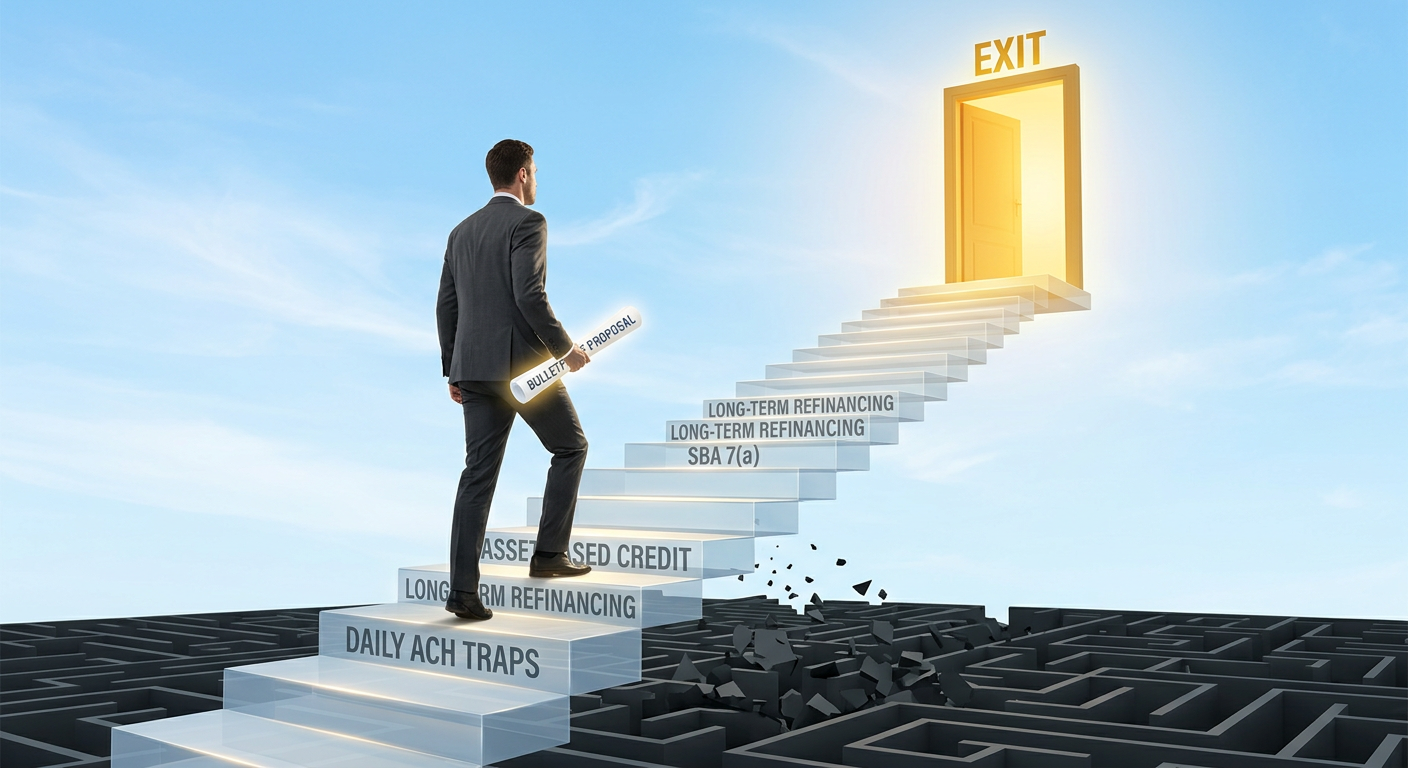
This article lays out a clear, three-step path out of that cycle: restructure what you owe today, look to quickly replace expensive short-term financing with longer and cheaper bridge financing and then graduate to a true credit facility with a private credit or commercial bank partner. Each step builds on the one before it, and together they can move your company from survival mode back to growth.
Most business owners know exactly what their last advance or short-term loan cost them on paper. Far fewer know what it cost them in practice. The factor rate, the origination fee and the frequent remittances are the visible part of the bill. The larger part shows up later, in thinner inventory, delayed hires, strained vendor relationships, skipped maintenance and an owner who spends more time managing cash than running the company.
This article is for owners who have taken on expensive, fast funding to get through a tight stretch and now feel the business working for the lender instead of the other way around. It is also for owners who are considering that kind of financing right now and want to understand what they are really signing up for.
What follows breaks down how short-term and stacked financing quietly reshapes business operations, why the true cost is almost always higher than the quoted cost and what practical steps you can take to stabilize cash flow, regain control and move toward capital that supports growth instead of draining it.
If your business is juggling several short-term loans, merchant cash advances, equipment financings and lines of credit, you already know the feeling. Money comes in, and before you can use it to grow, it is whisked away by ACH debits to a handful or more of transactional business funders and lenders. Business is profitable on paper, yet always short on cash.
There is a better business financing structure. The funding brokers and lenders you are working with now do not have the experience or ability to offer 24, 36 and 60-month terms on a business credit facility starting at 13% to 16% cost of capital. They are in the business of short-term, fast-moving and expensive capital, not long-term growth capital. By consolidating those individual transactional financings into a single, longer-term business private credit facility, many small and mid-sized businesses can reduce their cost of capital by one-half to two-thirds, dramatically lower their monthly and annual total debt service payments and free up cash that can go straight back into investment and operations.
This article explains how that works, why private credit investment funds and boutique commercial banks are often the right partners for it, and what the process looks like when an experienced business finance advisor manages the process on your behalf.
If your business has taken on expensive business debt like expensive term loans or merchant cash advances (MCAs) with rates that quietly eat your profit margins, you already know the feeling. It doesn't show up all at once. It shows up in the space between what you thought you'd have left over and what's actually sitting in the account on a Friday afternoon.
The good news is that expensive business debt is rarely a dead end. It's a solvable problem. But solving it takes more than hope, and it takes more than trusting the first friendly voice that calls you promising a way out. This article walks through what actually gets a business owner out of the expensive business debt cycle, and just as important, what keeps well-meaning business owners stuck in it for far longer than they need or want to be.
The problem is rarely that proper business financing doesn't exist. The problem is that most owners shop for it the same way they shop for office supplies: quickly, under pressure and based on whoever answers the phone first. That approach works fine for paper towels. It can be disastrous for capital.
This article walks through five of the most common and most expensive mistakes business owners make when securing funding. None of them are exotic. All of them are avoidable. And most of them share a root cause: treating financing as a transaction to be closed rather than a relationship to be managed. If you recognize your business in any of the sections below, that is not a reason for alarm, it is a reason to make one phone call and start correcting course before the next renewal, the next stack or the next "great rate" offer lands on your desk.
If you are currently paying excessive annualized rates on a 6 to 12-month payback period for business funding such as merchant cash advance (MCAs) or short-term business loans, you are not stuck, you are misinformed and have been misled. Many business owners with strong personal credit (680, 700 and higher) and a stable operating history are placed into expensive, short-term financing not because it is their best option, but because it is the fastest and most profitable option for the broker who arranged it.
This article pulls back the curtain on the specific tactics these brokers use, from the bait and switch to the fake “unsecured” loan pitch to the commission structure that quietly decides which lender gets your business. If you are currently shopping for capital, or you already have a deal on the table, understanding these tricks could save your company from a financing decision you cannot undo.
The critical error occurs when this temporary emergency capital becomes a permanent fixture on the corporate balance sheet. High-frequency payment structures, such as daily or weekly ACH withdrawals, create a highly volatile environment where capital behaves remarkably like a tightly stretched rubber band. The moment revenue enters the business operating accounts, it immediately snaps back to the aggressive creditors, leaving the operation starved for the very working capital it initially borrowed. This continuous, rapid outflow of cash paralyzes future growth, prevents strategic investment and places immense psychological strain on the leadership team trying to manage the daily chaos of low business liquidity.
You may be feeling the squeeze of business financing that was supposed to help you grow. Many business owners discover too late that the money they borrowed came with hidden costs that drain cash, disrupt operations and leave them more vulnerable post-transaction. The problem is rarely just the interest rate. It is the short payback period. The disconnect starts with the people and processes that stand between you and the longer-term, affordable business capital you need.
Business “funding” brokers present themselves as your advocates while collecting commissions from the lenders. Cash-flow lenders approve funding deals with underwriting that prioritizes volume over sustainability. The result is financing that extracts every available dollar of free cash flow and sometimes forces you to plug gaps with personal equity or high-interest credit cards. In the worst cases, you end up stacking new business debt just to service the old (reverse Ponzi scheme). This article explains how those dynamics work and what you can do to protect and fix your business balance sheet.
Let’s dismantle the most pervasive, dangerous and financially destructive myths currently surrounding business financing. By forcefully exposing the deceptive tactics and misleading rhetoric often employed by business funding brokers and aggressive alternative lenders, our primary goal is to empower you with the essential knowledge required to make highly informed and strategic business financial decisions. From exploring the dangerous illusion surrounding interest rates to uncovering the heavily disguised traps of revenue purchase factor rates and hidden broker commissions, we will systematically explore the critical nuances that ultimately dictate the true cost and operational impact when taking on business debt. Armed with the unvarnished and objective truth, you can more confidently and safely navigate the complex capital markets.
The world of business financing is littered with the corpses of companies that fundamentally misunderstood the mechanics of business debt leverage. Business owners frequently operate under the delusion that securing capital is the ultimate victory, completely ignoring the structural reality of the business debt they have just onboarded.
Today, mounting business debt is not just a symptom of poor sales and liquidity shortages; it is a systemic crisis driven by toxic lending products engineered to drain working capital at an unnatural velocity. When a company is suffocating under high business debt payments, the root cause is rarely the principal balance itself. The true killer is the payback structure. You are being destroyed by amortizations that are too short, designed to strip your business cash reserves before you can even deploy the capital for operational growth.
This creates a catastrophic operational environment where every dollar of incoming revenue is immediately cannibalized by aggressive business debt service payments. You are no longer running a business; you operate a highly stressful collection agency on behalf of your creditors. This relentless capital extraction triggers severe liquidity shortages, completely paralyzing your day-to-day operations. When you lack the cash to meet basic vendor obligations, float payroll or purchase inventory, stability vanishes. Growth becomes a mathematical impossibility. Outselling a structurally broken balance sheet and attempting to do so will likely result in accelerating your path to business “paper insolvency”.
Surviving this financial warfare requires an objective approach to your business liabilities. You cannot borrow your way out of a business debt trap with more short-term cash, and you cannot negotiate with predatory lenders using conventional corporate logic. The only path forward is a clinical, unapologetic restructuring of your existing obligations to secure a longer-term business debt payback horizon which frees up cash flow and bolsters overall liquidity.
The following blueprint dismantles the fatal errors that push mature businesses into the debt trap, exposes the lethal nature of short-term amortizations and outlines the exact tactical strikes required to force creditors to the table, halt the cash bleed and eventually permanently stabilize your balance sheet.
Running a small to medium-sized business is often heralded as a pursuit of ultimate freedom and boundless opportunity. Yet, beneath the veneer of entrepreneurial success lies a deeply hidden narrative that many founders face but few openly discuss. When a company's cash flow turns negative, the dream can rapidly transform into a relentless struggle for survival.
The pressure is magnified exponentially when the business is shackled by aggressive, short-term debt obligations. Capital that matures in a year or less, carrying astronomical annual costs, acts as a silent anchor, dragging down business cash flow, the balance sheet and the mental well-being of the leadership team.
The intersection of financial distress and psychological strain creates a profound emotional toll that reverberates through every aspect of a business owner's life. This is not merely a mathematical problem of revenues minus expenses; it is a daily, visceral experience of anxiety. Aggressive automatic clearing house (ACH) withdrawals systematically drain operating accounts, leaving the founder to agonizingly patch together payroll, vendor payments, and essential operational costs.
The mental bandwidth required to juggle these immediate crises strips away the capacity for strategic foresight, reducing brilliant innovators to panicked firefighters. The capital that was intended to bridge a temporary gap instead becomes a permanent crisis, suffocating the very enterprise it was supposed to save.
Acknowledging the depth of this struggle is the first necessary step toward reclaiming control. By dismantling the stigma associated with distressed balance sheets and aggressive debt, founders can begin to pivot from emotional paralysis to strategic action, ultimately charting a course toward cash flow stabilization and long-term structural health.
Faced with the immediate, pressing need to meet payroll, purchase essential inventory or execute on a massive new client contract, countless business leaders find themselves turning to the rapidly accessible, yet incredibly dangerous, world of high-cost, short-term financing. While these alternative financial products provide the illusion of immediate relief, they quickly reveal their true, parasitic nature and cause long-term issues by cannibalizing cash flow and then disrupting business operations.
Short-term business financing is engineered not to foster sustainable business growth, but to aggressively extract capital at exorbitant effective interest rates, often trapping the business in a relentless cycle of continuous borrowing just to simply service the crushing debt payment obligations.
The journey out of this high-interest, short-term business debt trap is not achieved by merely increasing sales or working harder; it requires a fundamental, strategic restructuring of the enterprise's entire balance sheet. The key to long-term survival and prosperity lies in successfully executing a pivot away from these toxic, short-term cash drains and transitioning toward sustainable, longer-term business financing solutions.
This transformative shift involves navigating the complex but incredibly rewarding landscapes of private credit markets, Small Business Investment Companies (SBICs) and advanced institutional lending facilities.
These longer-term solutions offer something the short-term market actively destroys: the gift of time. By amortizing business debt over several years rather than compressing it into a brutal 12-months or less, businesses can drastically reduce their monthly cash outlay, stabilize their operational liquidity, and reclaim the working capital necessary to actually execute their strategic vision.
When cash flow turns negative and liquidity completely dries up, standard management strategies are no longer sufficient. Drowning in business debt service while struggling with maxed-out credit lines and stressed vendors requires an immediate, aggressive shift toward crisis management and cash preservation.
There is absolutely no room for error when every available dollar is consumed by obligations, leaving operations starved of the capital needed to function and grow.
Surviving this critical juncture demands clear-headed leadership, rapid operational triage and a ruthless prioritization of financial stability over short-term growth. The objective must immediately shift from profitability to absolute liquidity. By executing a series of uncompromising turnaround protocols, ranging from renegotiating existing business debt and restructuring vendor payments to unlocking hidden assets and drastically reducing overhead, business owners can halt the terminal cash bleed.
By moving away from denial and confronting the stark mathematical realities of your balance sheet, you can execute a tactical defense of your core enterprise. This detailed roadmap is designed to pull your business back from the absolute brink, stabilize your operational foundation, and ultimately build a sustainable pathway toward financial recovery.
The distinction between a failing business and a failing capital structure is the most critical realization an entrepreneur can make when facing insolvency. These businesses all share the exact same core problem: at some point in the recent past, they hit a temporary revenue snag. Perhaps it was a seasonal dip, a delayed major contract, a sudden macroeconomic shift or a supply chain disruption.
Cash got tight. The traditional banking system, known for its slow underwriting and rigid criteria, was too slow to help. The only "help" available in that moment of desperation was a fast, easy, but ultimately predatory business financing instruments. This capital, often disguised as merchant cash advances or high-interest short-term loans, was injected to solve a temporary problem, but aggressive and unsustainable repayment terms turned a temporary cash flow hiccup into a permanent, existential crisis.
The path forward requires a radical shift in strategy and mindset. You cannot borrow your way out of a predatory business debt cycle with more short-term business debt. Instead, you must embark on a comprehensive balance sheet restructuring. These businesses need to rapidly boost their liquidity back to a healthy threshold of 10% to 15% percent of annual revenue. They must forcefully re-align business cash flow and business debt service payments to break the cycle of frequent remittances and return the operation to a cash flow positive state.
The ultimate goal is to completely reconstitute the business financials to more accurately represent the performance of the business. By doing so, you can elevate your enterprise out of the predatory alternative lending space and prepare for serious, productive discussions with institutional solutions. Entities such as private credit funds and Small Business Investment Companies (SBICs) offer the long-term business financing you actually need, providing sustainable amortizations of two, three, and five years, and even ten years for working capital (pending approval) and fifteen or twenty-five-year amortizations when leveraging commercial real estate assets.
When economic headwinds shift, market dynamics fluctuate, or unexpected operational hurdles arise, mounting business debt and accounts payable liabilities can rapidly become an overwhelming burden. Many business owners find themselves trapped in a stressful cycle of managing cash outflows just to keep the doors open, watching their hard-earned cash flow turn from positive to negative. When you are in this position, it can feel like you are running out of time and options, but the truth is that business debt itself is often not the problem rather, the structure (payback period and cost) of that business debt is what is suffocating your business.
Refinancing and restructuring your business debt properly is not merely about finding a new lender to pay off the old ones; it is a comprehensive, strategic process designed to realign your entire financial architecture. By approaching this transition systematically, you can mitigate operational risks, protect your equity and position your company for a sustainable, high-value recovery.
This guide outlines the exact, institutional-grade pathway to transition your business from negative cash flow back to positive, thriving territory. Through restructuring existing obligations, cleaning up your financial reporting and partnering with sophisticated private credit providers, you can unlock long-term, patient capital that recognizes the true underlying value of your enterprise.
As you read through this comprehensive guide, remember that financial distress is often a temporary state masking the true potential of your business's cash flow and EBITDA production. By taking proactive control of your company’s balance sheet, collaborating with experienced business financial advisors and presenting your company’s narrative in a language that sophisticated underwriters respect, you can build a stable liquidity cushion that safeguards your business for years to come. Let this be your roadmap out of the business debt trap and into a structured, well-capitalized and highly profitable future.
Business cash flow is the literal lifeblood that sustains operations, fuels expansion and keeps the doors open. When a sudden dip in revenue, an unexpected expense or a delayed client payment threatens this cash flow, business owners often find themselves in a state of high stress and vulnerability. In these moments of acute financial anxiety, the promise of quick, hassle-free capital can feel like a lifeline thrown to a drowning swimmer.
Unfortunately, lurking in the shadows of the “alternative” business financing industry is a highly coordinated ecosystem of predatory and opportunistic business funding companies and deceptive brokers. These actors are not looking to help your business grow; instead, they are engineered to exploit your financial desperation for their own astronomical gain. They employ high-pressure tactics, opaque contract terms and outright deception to trap well-meaning entrepreneurs in cycles of high-cost and high-payment business debt that frequently lead to negative cash flow, then operational distress and finally potential business insolvency and personal ruin.
To protect your hard-earned business, it is vital to understand the inner workings of this predatory funder and broker landscape. Let’s unmask the deceptive practices of business funding brokers, expose the destructive nature of the financial products they sell and explain how they systematically divert eligible borrowers away from safe, low-cost institutional capital like SBA loans and Private Credit business credit facilities to line their own pockets with exorbitant commissions paid by you.
The silent killer of small and medium-sized businesses isn't a lack of passion, a bad product or an unmotivated team. It is the suffocating, relentless chokehold of negative cash flow created by short-term debt amortizations and a ridiculously high cost of capital. Every single day, hundreds of thousands of business owners wake up to watch their hard-earned revenues drained from their bank accounts by weekly ACH withdrawals. What began as a quick fix to cover a cash flow gap has mutated into a chronic disease that starves the business of the oxygen it needs to survive, let alone grow.
If you are constantly looking at your bank balance with a knot in your stomach, realizing that your short-term bridge business loans, merchant cash advances (MCAs), or high-interest business lines of credit are eating your entire operating margin, it is time to stop playing defense. Defensive management by cutting marketing, laying off valuable staff or delaying vendor payments is a slow march towards insolvency.
To save your business and reclaim your peace of mind, you must shift to an aggressive, offensive strategy. You must take immediate action to restructure your existing debts and refinance them into longer-term, lower-cost facilities.
In the sections below, we will lay out an aggressive, unvarnished blueprint designed specifically for small and medium-sized business owners who are tired of being held hostage by opportunistic business lenders. We will examine the mechanics of how you got trapped, how to properly confront your current creditors and how to successfully execute a long-term refinancing strategy that returns cash flow to where it belongs: your business. Stop letting lenders dictate your survival.
In need of business capital, but walking through a minefield? The pressure of maintaining cash flow, funding inventory, meeting payroll obligations or trying to scale can make you vulnerable, and there is an entire ecosystem of financial vultures waiting to exploit that exact vulnerability. They smell your stress from a mile away, and they mask their predatory intentions behind polished websites, friendly phone calls and the false promise of "fast, hassle-free funding."
The truth is brutal: the transactional business funding broker is not your friend, they are not your partner and they do not care if your business survives the next six months. They are commission-hungry middlemen whose entire business model relies on trapping you in high-interest, short-term debt that lines their pockets while slowly choking your operations to death. How does your funding broker get paid?
To them, your business is not a dream or a legacy, it is merely a transaction to be milked for the absolute maximum commission before they vanish into the shadows to hunt their next victim.
To protect the Company you have poured your blood, sweat, and tears into, you must learn to see through the lies. You must understand the predatory mechanics of the transactional funding broker, expose the toxic conflict of interest that drives their every recommendation, and discover why a dedicated business finance and strategy advisor is the only true ally you can trust to sit on your side of the table.
When short-term capital is used to patch long-term operational needs, what seemed like a quick fix can rapidly spiral into a severe cash flow crisis. Escaping this cycle requires more than just another loan; it demands strategic restructuring, expert financial guidance and a sustainable path forward.
At Bernarsky Advisors, we align with your company as its trusted advisor and dedicated problem-solver to help you navigate these complex business finance and strategic waters. We work closely with you to dissect your current business debt structures, design a viable near-term 13-week restructuring plan and take you to the private credit markets to attempt to secure the refinancing and growth capital necessary to revitalize your business.
Institutional and private credit funds that we introduce you to have the ability to provide 24, 30, 36 and 60-month private credit facilities at market rates of 14% to 18% right now. As long as your business has strong cash flows, EBITDA and net profit margins, you may qualify to trade fast, expensive capital with long-term, patient capital.
This comprehensive guide outlines how you can break free from short-term and high-cost business debt, rebuild your company’s financial foundation, and reclaim control over your business's future.
The following is a case study from one of our recent business refinancing and restructuring engagements. The core issue is high-cost, short-payback financing (MCAs) are mis-aligned with the cash flow of the business, requiring payments in excess of what the business generates. You will see how financing like MCAs and other short-term and high-cost financing can quickly erode and destroy a company’s financial health.
An analysis of the two Merchant Cash Advance (MCA) agreements reveals that their concurrent execution will place an immediate, unsustainable and highly destructive financial burden on the business.
The test-case business generates a healthy annual operating net income of $800,000 on approx. $15M of top line revenue (with a ~11.0% EBITDA margin), translating to a weekly debt service capacity of $15,385. However, the combined weekly debt service of two MCA financings during the first 30 weeks is $47,985 per week or more than three times (3.12x) what the business's operations can support in business debt service payments.
Because operations can only cover a small fraction of the weekly payments, the business is forced to use the very cash it just received / financed to pay back the lenders. Rather than injecting $1,256,500 in net growth capital, $1,129,742 of the funded principal must be immediately recycled and returned as business debt payments. This leaves only $126,758 of actual net usable capital, while saddling the business with $565,550 in high-cost financing fees and an effective annualized APR of up to 164%.
Managing the delicate balance between business operational growth and business debt obligations is an ongoing, high-stakes challenge. In a current economic environment characterized by fluctuating interest rates and tightening credit markets, relying on traditional, short-term high-cost business debt can severely restrict a company's ability to maneuver, invest, and ultimately thrive.
Often, business owners find themselves trapped in a cycle of high monthly payments and rigid loan structures that drain liquidity, working capital and stifle innovation. However, there is a transformative path forward. By strategically refinancing business debt, restructuring amortization schedules and aligning with the right financial partners, business owners can dramatically reduce their cost of capital and unlock the vital cash flow necessary for sustainable expansion.
The journey toward financial optimization is not merely about finding a lower interest rate; it is about fundamentally changing the way a business interacts with its capital base. Traditional banking institutions often treat lending as a purely transactional endeavor, characterized by inflexible underwriting standards and a lack of deep understanding regarding a specific business's operational risks and opportunities.
In contrast, modern refinancing strategies emphasize the establishment of long-term credit facilities with dedicated capital partners. These partners, particularly within the private credit sector, offer a level of flexibility and risk tolerance that traditional banks simply cannot match. They take the time to comprehensively understand the nuances of your business model, your risk management strategies, and your long-term vision, transforming business debt from a burden into a powerful tool for strategic growth.
This article is designed to navigate small and medium-sized enterprise owners through the multifaceted landscape of business debt refinancing. We will explore the profound benefits of extending loan terms to lower monthly payments, the strategies required to slash capital costs by more than fifty percent and the critical importance of building enduring relationships with sophisticated capital providers.
Furthermore, we will delve into specialized alternative funding avenues, including Business Development Companies, Community Development Financial Institutions and Small Business Investment Companies, which offer unique advantages for the right borrowers. Finally, we will examine why partnering with a skilled business finance advisor is the crucial linchpin in securing these transformative private credit relationships and ensuring your business is positioned for long-term prosperity.
The landscape of American entrepreneurship is currently undergoing a profound and unprecedented transformation, one that is largely hidden from the daily headlines but felt acutely in the offices, warehouses, and storefronts of small to medium-sized enterprises across the nation. For generations, the small business sector has been celebrated as the indisputable backbone of the United States economy, serving as the primary engine for job creation, local community development, and grassroots innovation.
However, beneath the surface of this celebrated narrative lies a brewing storm of financial distress, driven by systemic shifts in how capital is accessed, structured, and managed. We are standing at the precipice of what can only be described as a reckoning a critical juncture where the financial paradigms of the past two decades are colliding violently with the stark realities of sustainable business operations.
This reckoning is not the result of a sudden macroeconomic shock, nor is it the product of a singular catastrophic event like the recent global pandemic. Instead, it is the culmination of years of structural changes in the lending ecosystem, characterized most notably by the explosive growth of alternative, high-cost financing models.
Small business owners, often starved of traditional banking resources and desperate for working capital to navigate volatile markets, have increasingly turned to fast, accessible, but deeply punitive funding mechanisms. As these financial instruments mature and compound, they are fundamentally altering the life cycle of the American small business.
We are transitioning from an era where businesses failed primarily due to lack of market demand, to a paradigm where thriving, revenue-generating companies are being suffocated by the very capital they borrowed to survive.
For the small and medium-sized business owner reading this, the following analysis is designed to serve as both a mirror and a map. It reflects the harsh realities of the current financial ecosystem, validating the immense pressures and unique challenges you may be facing on a daily basis. More importantly, it provides a strategic framework for understanding these macroeconomic forces and navigating your enterprise out of danger.
By dissecting the mechanics of the "Merchant Cash Advance" era, analyzing the critical collateral gaps, acknowledging the severe psychological toll on leadership, and outlining a path toward radical financial transparency, this paper aims to equip you with the knowledge necessary to restructure, survive, and ultimately reclaim your company's financial independence.
It’s a story we see every day: a business, forged through years of dedication and hard work, stands as a pillar of its community. It has survived economic downturns, celebrated a decade or more in operation, and generates what should be a healthy revenue stream. Yet, behind the scenes, the owner is fighting a silent, relentless battle. Cash flow is a constant struggle, growth is stalled, and a sense of being trapped is setting in. This isn't the story of a failing business; it's the story of a successful business caught in a dysfunctional financial structure, often unknowingly pulled into a cycle of high-cost, high-payment business debt, loans and leases that slowly strangles its future growth potential.
This article is for you, the seasoned business owner who recognizes this struggle. You’ve poured your life into your company, and you have the revenue to prove it. Yet, you find yourself overwhelmed by business debt obligations, hounded by aggressive lenders and unsure of the next step. You may have even taken out a short-term loan or financing like a Merchant Cash Advance (MCA) out of necessity, only to find yourself in a deeper hole.
We want you to know that not only is your situation common, but it is also solvable. Your years of experience, established operations, infrastructure and even your personal financial discipline are powerful assets waiting to be leveraged.
The path forward is not about finding another quick fix or a slightly better short-term and high-interest loan. It’s about a strategic reset.
It requires understanding the mechanics of the business debt amortization trap you're in, recognizing the hidden value within your business, and engaging with a partner who can provide a comprehensive strategy, not just a product. This guide will walk you through the steps to reclaim your business financial freedom, restructure and potentially refinance your obligations for sustainable growth and turn your established business back into the vehicle for success it was before business debt leverage became an issue.
For many business owners, the pursuit of growth and the need to manage day-to-day operational expenses can lead down a perilous financial path. In an environment where traditional bank loans are increasingly difficult to secure, alternative financing options have surged in popularity. These alternatives, often promising quick access to capital with minimal paperwork, can seem like a lifeline.
However, many of these financial products come with a hidden and often fatal flaw: aggressive repayment schedules, typically in the form of weekly or even daily withdrawals from a business’s bank account. This relentless and frequent siphoning of cash can trigger a devastating cycle of liquidity erosion, slowly starving a business of the very lifeblood it needs to survive.
This article delves into the insidious nature of high-frequency debt repayments and their catastrophic impact on a business's financial health. We will explore how what starts as a seemingly manageable solution can quickly devolve into a "death spiral" of cash flow shortages, operational compromises, and ultimately, business failure. This is not a theoretical discussion; it is a harsh reality for countless entrepreneurs who have watched their dreams crumble under the weight of an unsustainable business debt burden. By understanding the mechanics of this silent killer, business owners can learn to identify the warning signs, navigate the treacherous waters of alternative lending and implement strategies to protect their enterprises from financial ruin.
We will dissect the journey from the initial allure of easy money to the final, painful stages of insolvency. We will cover the psychological toll this process takes on entrepreneurs, the critical early warning signs that are often missed and the potential strategies for pulling a business back from the brink. The goal is to provide a comprehensive guide for any business owner who is feeling the squeeze of business debt repayment, offering not just a diagnosis of the problem, but also a roadmap toward recovery and the foundation for building a more financially resilient and sustainable business for the future.