Drowning in Business Debt? Cash flow issues? We can help you. Refinance. Restructure. Reorganize.
Most business owners think about business debt refinancing only when something feels wrong: a payment that stings, a rate that seems high or a month where the account balance dips lower than it should. By then, the best options have often narrowed. The more interesting truth is that a business refinancing window opens quietly, usually when things are going reasonably well, and it tends to close before most owners notice it was ever there as cash flow tightens.
At the center of the business debt refinancing window sits a relationship few owners examine closely: how the schedule of their business loan amortization lines up with the actual rhythm of their business cash flow. When those two move together, business debt becomes a tool. When they drift apart, even a modestly sized business loan can feel heavier than it really is.
This article walks through how that business debt amortization mismatch develops, the signals that suggest a business debt refinancing window is open, and the practical strategies business owners use to realign their business debt payback with the way cash flow actually moves through their company.
Your company is profitable. Your customers are paying. And your bank balance still drains toward zero before every payroll. That is not bad luck, and it is not a sales problem. In most cases, it is a business debt structural problem causing a business cash flow problem, and it will not fix itself.
Tight business cash flow caused by a badly structured business debt load is one of the most fixable problems a small or medium-sized company can face. The revenue is already there. The customers are already there. What has to change is the shape of the obligations sitting on top of them. Build the map. Set the strategy. Bring in the right help. Then rebuild a business debt structure that works for your company instead of against it and take back control of your business cash flow.
This article lays out exactly where business debt structures break down, how to find the breaks in your own company and the aggressive moves owners use to rebuild business cash flow and take back control of your operations and your company.
Your business may be in immediate danger. This is not a drill, and it is not a gentle suggestion to review your accounting practices. If you are reading this because your business is drowning in debt and negative cash flow, you are standing on the precipice of total insolvency, and the ground is crumbling beneath your feet.
The sleepless nights, the dread of opening your email, the pit in your stomach when the phone rings—these are not just symptoms of stress; they are the warning lights of a catastrophic engine failure.
Your business is heading towards dying. It is harsh to say, but if you do not acknowledge the severity of your situation, you may risk losing everything you have built. The time for optimism and "waiting for the big deal to close" is over. You are in a war for business survival.
There is a better way. Longer-term business financing, structured properly, can often cost roughly half as much as high-cost short-term debt and stretch repayment over years instead of months. That combination can cut your monthly payments dramatically and hand control of your business cash flow and operations back to you.
This article explains how short-term and expensive business debt traps work, what longer-term business financing look like, how to compare offers honestly and how to prepare your business to qualify. Before you sign for another dollar of business financing, read this first. The right decision today could save your business on costs and cash flow, and a great deal of stress.
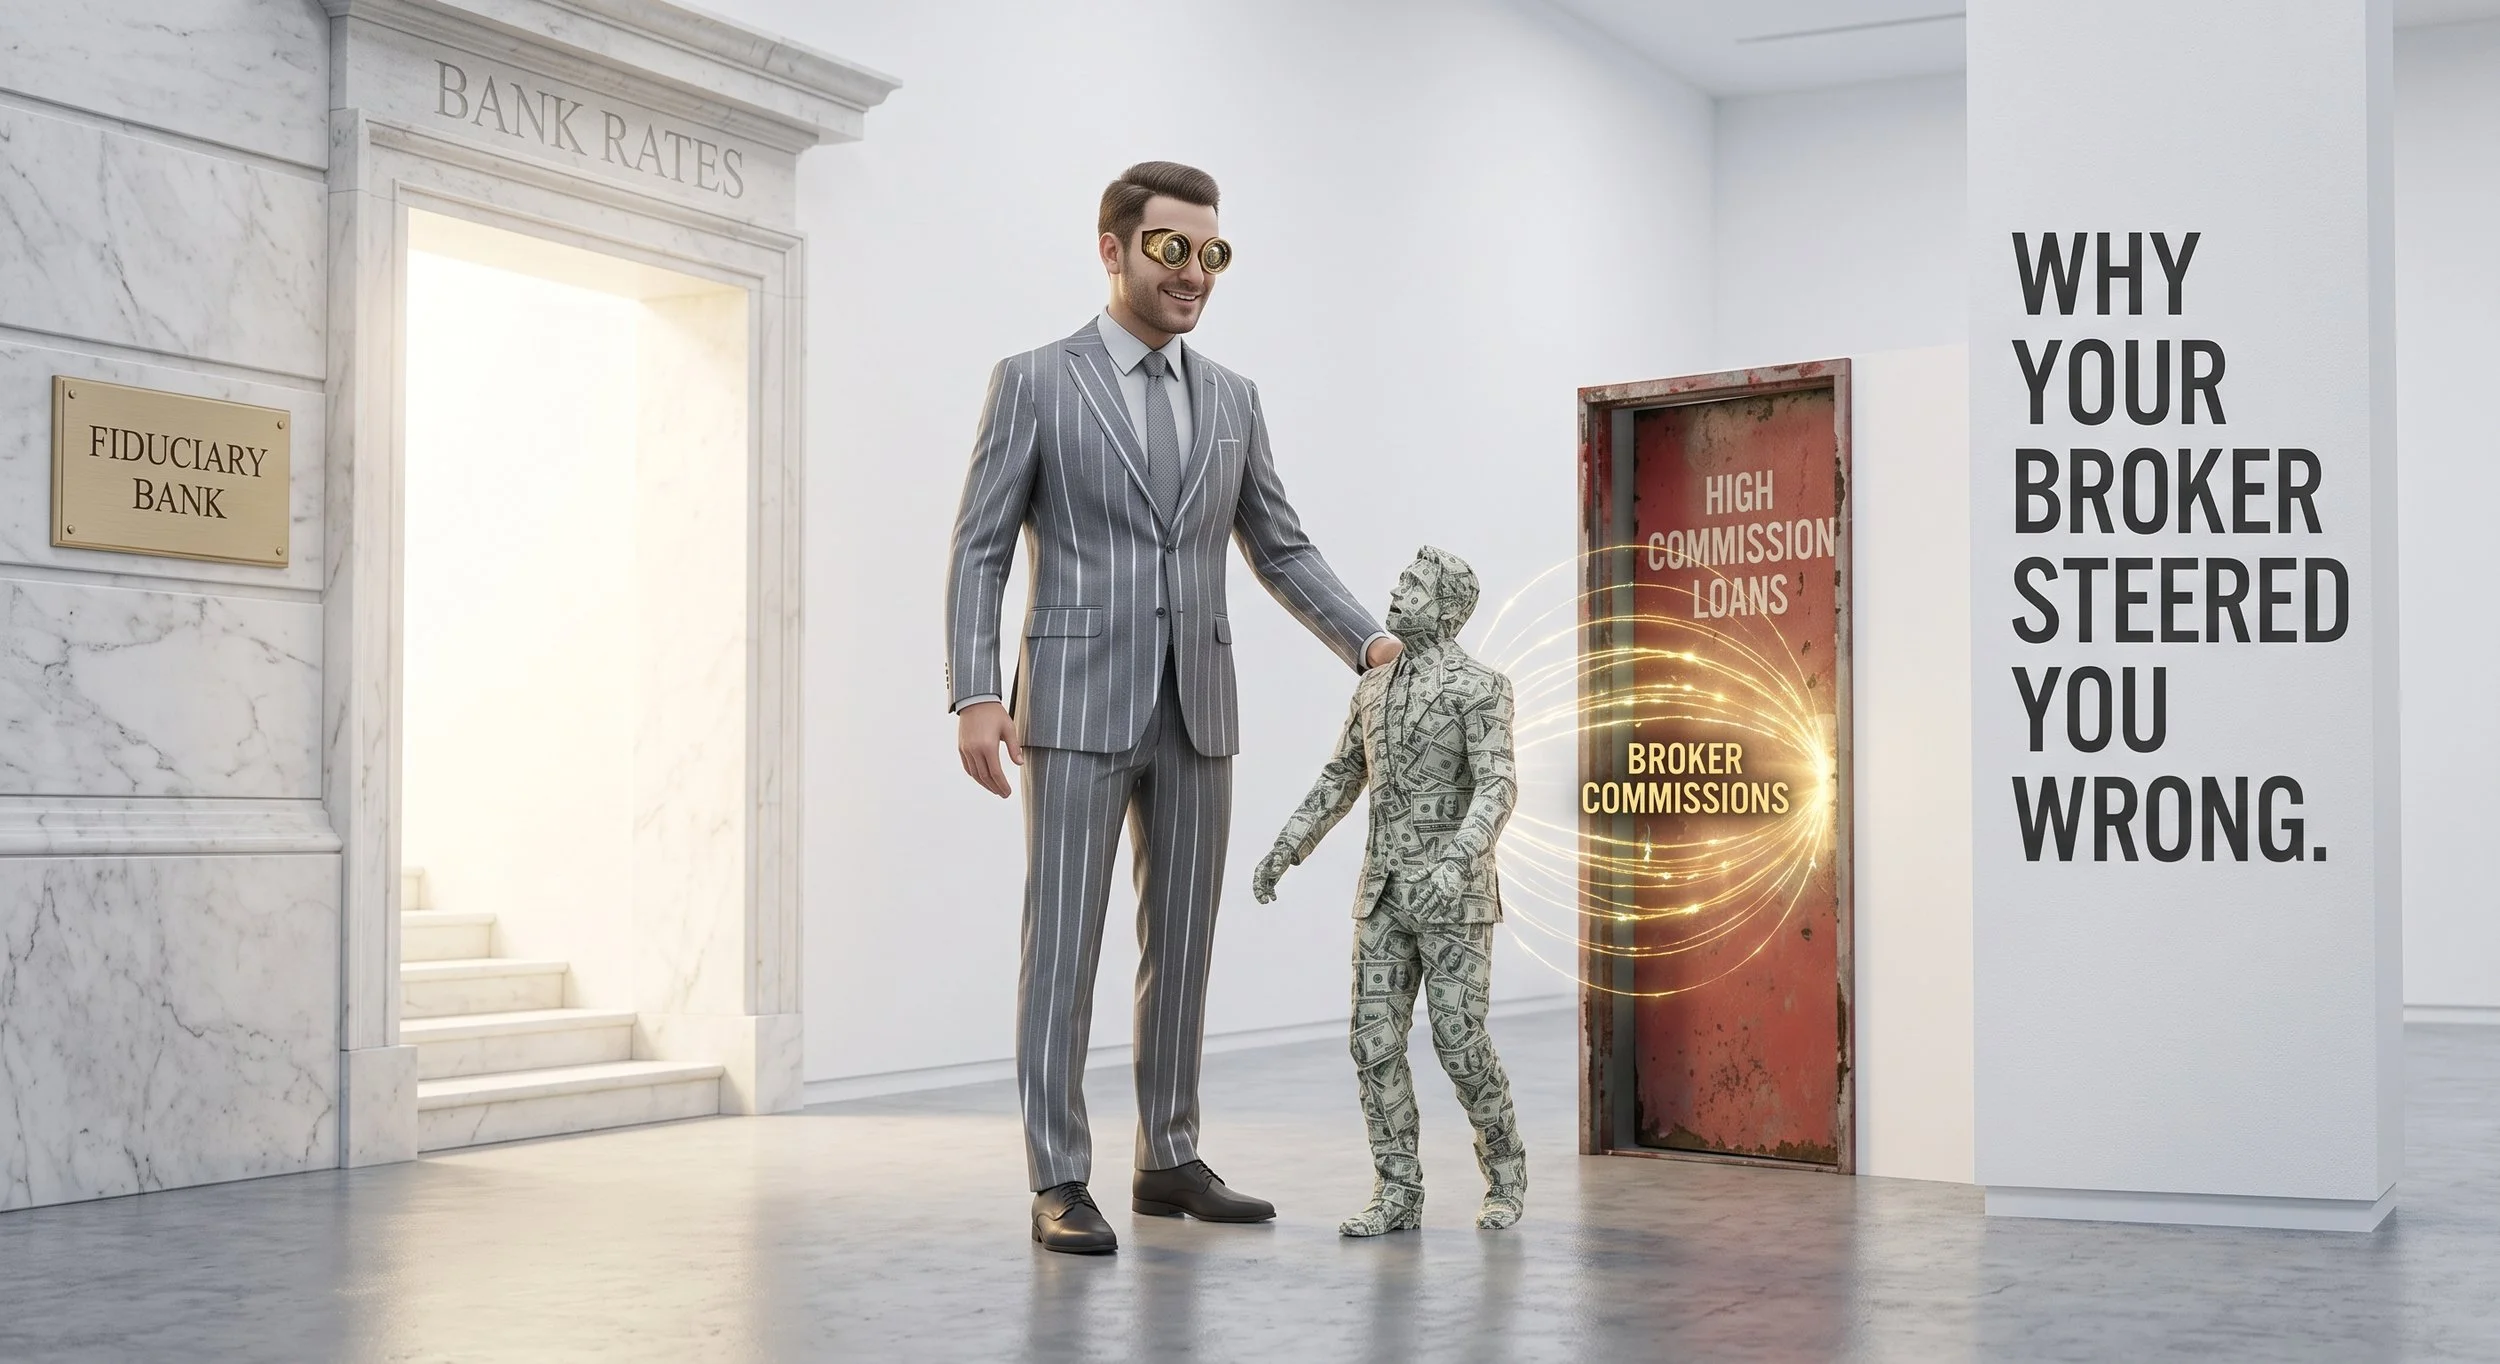
When the payments on a costly business loan or merchant cash advance (MCA) start squeezing your business, the first instinct is to call the person who arranged it. They know your file, they know the lender, and they answered the phone quickly the last time you needed money. It feels like the natural place to start.
It is usually the wrong place. Most financing brokers are paid when new money is placed, not when your total cost goes down. They also have every reason to defend the deal they already sold you. Asking them for a way out is like asking the salesperson who sold you the car with the bad transmission whether you should buy another car from the same lot.
This article explains why that conflict exists, how to recognize when you are being steered instead of helped, and what a genuinely independent business finance advisor can do that a broker cannot. If your business is carrying debt that feels heavier every week, read on before you make the next call.