Hiring a business advisor can bring substantial value to your business, especially when navigating complex challenges, growth opportunities, or strategic pivots.
Here are some compelling reasons to consider working with a business advisor:
1. Objective Perspective
Business advisors provide an impartial, third-party perspective, helping you identify blind spots and offering constructive feedback on your decisions. This can be invaluable in spotting issues or opportunities you might overlook.
2. Expertise and Experience
Advisors often have extensive experience across various industries and situations. They bring knowledge in areas like finance, marketing, operations, and management, which can help address specific challenges or plan for future growth.
3. Strategic Planning
A good business advisor can help you build or refine your business strategy, setting clear objectives and creating a roadmap to achieve them. They help ensure your goals are realistic, measurable, and aligned with market trends and internal capabilities.
4. Improved Financial Management
Advisors can assist with budgeting, cash flow management, and financial planning, helping you make sound financial decisions. They often bring analytical tools to help interpret financial data, cut costs, and identify revenue growth opportunities.
5. Enhanced Decision-Making
By providing industry insights and expertise, advisors empower you to make well-informed decisions faster. They can also guide risk assessment, helping you anticipate the consequences of major choices.
6. Access to Networks and Resources
Advisors often have strong networks of business contacts, including potential partners, investors, vendors, and even clients. These connections can open new doors and provide resources you might not have had access to otherwise.
7. Efficient Problem Solving
When specific issues arise, an advisor’s experience enables them to propose practical solutions and implement effective action plans. They bring proven frameworks and methodologies to address and resolve challenges efficiently.
8. Scalability and Growth
Advisors help identify opportunities for sustainable growth, whether through new markets, products, or operational improvements. They can guide scaling processes, avoiding common pitfalls that can arise when expanding too quickly or without proper planning.
9. Accountability Partner
A business advisor can hold you accountable for meeting your goals, pushing you to follow through on your strategic plans. This accountability can be motivating and can lead to better productivity and execution across the business.
10. Reduced Risk
Advisors help assess and manage risks, from financial to operational to market risks, ensuring you are well-prepared for uncertainties. They bring risk-mitigation strategies and industry best practices, which can protect your business from costly missteps.
11. Customized Guidance and Training
Advisors can provide tailored advice based on your business’s unique needs and train your team in specific areas. This helps build internal capabilities, ultimately making your team stronger and more self-sufficient.
A business advisor brings expertise, objectivity, and strategic insights, allowing you to make confident decisions, avoid common pitfalls, and focus on long-term success.
Whether you’re a startup or an established company, a good business advisor can become a crucial asset for navigating challenges and seizing opportunities.
Read some other recent business articles:
If you are currently paying excessive annualized rates on a 6 to 12-month payback period for business funding such as merchant cash advance (MCAs) or short-term business loans, you are not stuck, you are misinformed and have been misled. Many business owners with strong personal credit (680, 700 and higher) and a stable operating history are placed into expensive, short-term financing not because it is their best option, but because it is the fastest and most profitable option for the broker who arranged it.
This article pulls back the curtain on the specific tactics these brokers use, from the bait and switch to the fake “unsecured” loan pitch to the commission structure that quietly decides which lender gets your business. If you are currently shopping for capital, or you already have a deal on the table, understanding these tricks could save your company from a financing decision you cannot undo.
The critical error occurs when this temporary emergency capital becomes a permanent fixture on the corporate balance sheet. High-frequency payment structures, such as daily or weekly ACH withdrawals, create a highly volatile environment where capital behaves remarkably like a tightly stretched rubber band. The moment revenue enters the business operating accounts, it immediately snaps back to the aggressive creditors, leaving the operation starved for the very working capital it initially borrowed. This continuous, rapid outflow of cash paralyzes future growth, prevents strategic investment and places immense psychological strain on the leadership team trying to manage the daily chaos of low business liquidity.
You may be feeling the squeeze of business financing that was supposed to help you grow. Many business owners discover too late that the money they borrowed came with hidden costs that drain cash, disrupt operations and leave them more vulnerable post-transaction. The problem is rarely just the interest rate. It is the short payback period. The disconnect starts with the people and processes that stand between you and the longer-term, affordable business capital you need.
Business “funding” brokers present themselves as your advocates while collecting commissions from the lenders. Cash-flow lenders approve funding deals with underwriting that prioritizes volume over sustainability. The result is financing that extracts every available dollar of free cash flow and sometimes forces you to plug gaps with personal equity or high-interest credit cards. In the worst cases, you end up stacking new business debt just to service the old (reverse Ponzi scheme). This article explains how those dynamics work and what you can do to protect and fix your business balance sheet.
Let’s dismantle the most pervasive, dangerous and financially destructive myths currently surrounding business financing. By forcefully exposing the deceptive tactics and misleading rhetoric often employed by business funding brokers and aggressive alternative lenders, our primary goal is to empower you with the essential knowledge required to make highly informed and strategic business financial decisions. From exploring the dangerous illusion surrounding interest rates to uncovering the heavily disguised traps of revenue purchase factor rates and hidden broker commissions, we will systematically explore the critical nuances that ultimately dictate the true cost and operational impact when taking on business debt. Armed with the unvarnished and objective truth, you can more confidently and safely navigate the complex capital markets.
The world of business financing is littered with the corpses of companies that fundamentally misunderstood the mechanics of business debt leverage. Business owners frequently operate under the delusion that securing capital is the ultimate victory, completely ignoring the structural reality of the business debt they have just onboarded.
Today, mounting business debt is not just a symptom of poor sales and liquidity shortages; it is a systemic crisis driven by toxic lending products engineered to drain working capital at an unnatural velocity. When a company is suffocating under high business debt payments, the root cause is rarely the principal balance itself. The true killer is the payback structure. You are being destroyed by amortizations that are too short, designed to strip your business cash reserves before you can even deploy the capital for operational growth.
This creates a catastrophic operational environment where every dollar of incoming revenue is immediately cannibalized by aggressive business debt service payments. You are no longer running a business; you operate a highly stressful collection agency on behalf of your creditors. This relentless capital extraction triggers severe liquidity shortages, completely paralyzing your day-to-day operations. When you lack the cash to meet basic vendor obligations, float payroll or purchase inventory, stability vanishes. Growth becomes a mathematical impossibility. Outselling a structurally broken balance sheet and attempting to do so will likely result in accelerating your path to business “paper insolvency”.
Surviving this financial warfare requires an objective approach to your business liabilities. You cannot borrow your way out of a business debt trap with more short-term cash, and you cannot negotiate with predatory lenders using conventional corporate logic. The only path forward is a clinical, unapologetic restructuring of your existing obligations to secure a longer-term business debt payback horizon which frees up cash flow and bolsters overall liquidity.
The following blueprint dismantles the fatal errors that push mature businesses into the debt trap, exposes the lethal nature of short-term amortizations and outlines the exact tactical strikes required to force creditors to the table, halt the cash bleed and eventually permanently stabilize your balance sheet.
Running a small to medium-sized business is often heralded as a pursuit of ultimate freedom and boundless opportunity. Yet, beneath the veneer of entrepreneurial success lies a deeply hidden narrative that many founders face but few openly discuss. When a company's cash flow turns negative, the dream can rapidly transform into a relentless struggle for survival.
The pressure is magnified exponentially when the business is shackled by aggressive, short-term debt obligations. Capital that matures in a year or less, carrying astronomical annual costs, acts as a silent anchor, dragging down business cash flow, the balance sheet and the mental well-being of the leadership team.
The intersection of financial distress and psychological strain creates a profound emotional toll that reverberates through every aspect of a business owner's life. This is not merely a mathematical problem of revenues minus expenses; it is a daily, visceral experience of anxiety. Aggressive automatic clearing house (ACH) withdrawals systematically drain operating accounts, leaving the founder to agonizingly patch together payroll, vendor payments, and essential operational costs.
The mental bandwidth required to juggle these immediate crises strips away the capacity for strategic foresight, reducing brilliant innovators to panicked firefighters. The capital that was intended to bridge a temporary gap instead becomes a permanent crisis, suffocating the very enterprise it was supposed to save.
Acknowledging the depth of this struggle is the first necessary step toward reclaiming control. By dismantling the stigma associated with distressed balance sheets and aggressive debt, founders can begin to pivot from emotional paralysis to strategic action, ultimately charting a course toward cash flow stabilization and long-term structural health.
Faced with the immediate, pressing need to meet payroll, purchase essential inventory or execute on a massive new client contract, countless business leaders find themselves turning to the rapidly accessible, yet incredibly dangerous, world of high-cost, short-term financing. While these alternative financial products provide the illusion of immediate relief, they quickly reveal their true, parasitic nature and cause long-term issues by cannibalizing cash flow and then disrupting business operations.
Short-term business financing is engineered not to foster sustainable business growth, but to aggressively extract capital at exorbitant effective interest rates, often trapping the business in a relentless cycle of continuous borrowing just to simply service the crushing debt payment obligations.
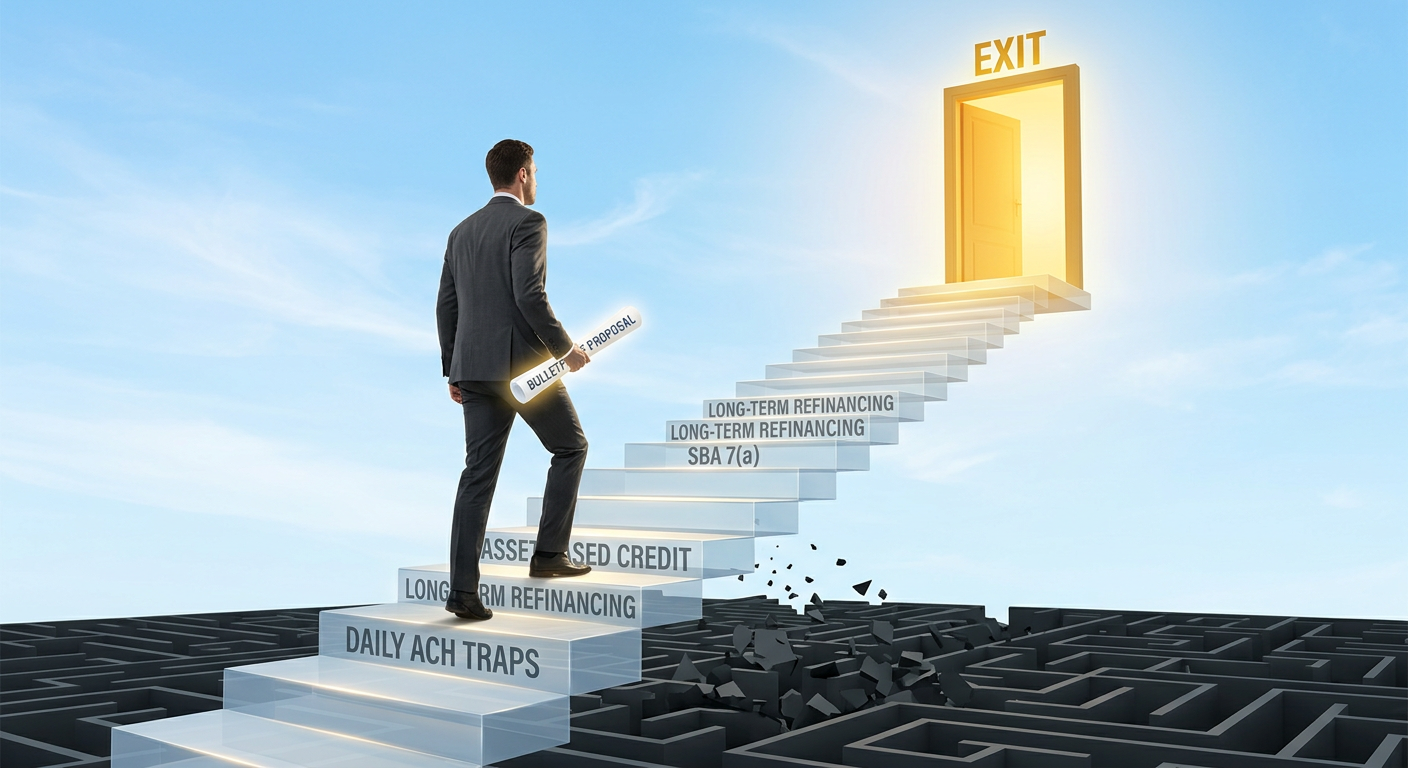
The journey out of this high-interest, short-term business debt trap is not achieved by merely increasing sales or working harder; it requires a fundamental, strategic restructuring of the enterprise's entire balance sheet. The key to long-term survival and prosperity lies in successfully executing a pivot away from these toxic, short-term cash drains and transitioning toward sustainable, longer-term business financing solutions.
This transformative shift involves navigating the complex but incredibly rewarding landscapes of private credit markets, Small Business Investment Companies (SBICs) and advanced institutional lending facilities.
These longer-term solutions offer something the short-term market actively destroys: the gift of time. By amortizing business debt over several years rather than compressing it into a brutal 12-months or less, businesses can drastically reduce their monthly cash outlay, stabilize their operational liquidity, and reclaim the working capital necessary to actually execute their strategic vision.
When cash flow turns negative and liquidity completely dries up, standard management strategies are no longer sufficient. Drowning in business debt service while struggling with maxed-out credit lines and stressed vendors requires an immediate, aggressive shift toward crisis management and cash preservation.
There is absolutely no room for error when every available dollar is consumed by obligations, leaving operations starved of the capital needed to function and grow.
Surviving this critical juncture demands clear-headed leadership, rapid operational triage and a ruthless prioritization of financial stability over short-term growth. The objective must immediately shift from profitability to absolute liquidity. By executing a series of uncompromising turnaround protocols, ranging from renegotiating existing business debt and restructuring vendor payments to unlocking hidden assets and drastically reducing overhead, business owners can halt the terminal cash bleed.
By moving away from denial and confronting the stark mathematical realities of your balance sheet, you can execute a tactical defense of your core enterprise. This detailed roadmap is designed to pull your business back from the absolute brink, stabilize your operational foundation, and ultimately build a sustainable pathway toward financial recovery.
The distinction between a failing business and a failing capital structure is the most critical realization an entrepreneur can make when facing insolvency. These businesses all share the exact same core problem: at some point in the recent past, they hit a temporary revenue snag. Perhaps it was a seasonal dip, a delayed major contract, a sudden macroeconomic shift or a supply chain disruption.
Cash got tight. The traditional banking system, known for its slow underwriting and rigid criteria, was too slow to help. The only "help" available in that moment of desperation was a fast, easy, but ultimately predatory business financing instruments. This capital, often disguised as merchant cash advances or high-interest short-term loans, was injected to solve a temporary problem, but aggressive and unsustainable repayment terms turned a temporary cash flow hiccup into a permanent, existential crisis.
The path forward requires a radical shift in strategy and mindset. You cannot borrow your way out of a predatory business debt cycle with more short-term business debt. Instead, you must embark on a comprehensive balance sheet restructuring. These businesses need to rapidly boost their liquidity back to a healthy threshold of 10% to 15% percent of annual revenue. They must forcefully re-align business cash flow and business debt service payments to break the cycle of frequent remittances and return the operation to a cash flow positive state.
The ultimate goal is to completely reconstitute the business financials to more accurately represent the performance of the business. By doing so, you can elevate your enterprise out of the predatory alternative lending space and prepare for serious, productive discussions with institutional solutions. Entities such as private credit funds and Small Business Investment Companies (SBICs) offer the long-term business financing you actually need, providing sustainable amortizations of two, three, and five years, and even ten years for working capital (pending approval) and fifteen or twenty-five-year amortizations when leveraging commercial real estate assets.
When economic headwinds shift, market dynamics fluctuate, or unexpected operational hurdles arise, mounting business debt and accounts payable liabilities can rapidly become an overwhelming burden. Many business owners find themselves trapped in a stressful cycle of managing cash outflows just to keep the doors open, watching their hard-earned cash flow turn from positive to negative. When you are in this position, it can feel like you are running out of time and options, but the truth is that business debt itself is often not the problem rather, the structure (payback period and cost) of that business debt is what is suffocating your business.
Refinancing and restructuring your business debt properly is not merely about finding a new lender to pay off the old ones; it is a comprehensive, strategic process designed to realign your entire financial architecture. By approaching this transition systematically, you can mitigate operational risks, protect your equity and position your company for a sustainable, high-value recovery.
This guide outlines the exact, institutional-grade pathway to transition your business from negative cash flow back to positive, thriving territory. Through restructuring existing obligations, cleaning up your financial reporting and partnering with sophisticated private credit providers, you can unlock long-term, patient capital that recognizes the true underlying value of your enterprise.
As you read through this comprehensive guide, remember that financial distress is often a temporary state masking the true potential of your business's cash flow and EBITDA production. By taking proactive control of your company’s balance sheet, collaborating with experienced business financial advisors and presenting your company’s narrative in a language that sophisticated underwriters respect, you can build a stable liquidity cushion that safeguards your business for years to come. Let this be your roadmap out of the business debt trap and into a structured, well-capitalized and highly profitable future.
Business cash flow is the literal lifeblood that sustains operations, fuels expansion and keeps the doors open. When a sudden dip in revenue, an unexpected expense or a delayed client payment threatens this cash flow, business owners often find themselves in a state of high stress and vulnerability. In these moments of acute financial anxiety, the promise of quick, hassle-free capital can feel like a lifeline thrown to a drowning swimmer.
Unfortunately, lurking in the shadows of the “alternative” business financing industry is a highly coordinated ecosystem of predatory and opportunistic business funding companies and deceptive brokers. These actors are not looking to help your business grow; instead, they are engineered to exploit your financial desperation for their own astronomical gain. They employ high-pressure tactics, opaque contract terms and outright deception to trap well-meaning entrepreneurs in cycles of high-cost and high-payment business debt that frequently lead to negative cash flow, then operational distress and finally potential business insolvency and personal ruin.
To protect your hard-earned business, it is vital to understand the inner workings of this predatory funder and broker landscape. Let’s unmask the deceptive practices of business funding brokers, expose the destructive nature of the financial products they sell and explain how they systematically divert eligible borrowers away from safe, low-cost institutional capital like SBA loans and Private Credit business credit facilities to line their own pockets with exorbitant commissions paid by you.